Call us
01242 697821

Blogs

Keep up to date with the latest news and our guides on all things mortgages. 

Understanding Tax Calculations and Tax Year Overviews

If you’re applying for a mortgage, you may have come across the terms Tax Calculations, SA302 and Tax Year Overview. These documents play a crucial role in the mortgage application process, especially if you’re self-employed or receive rental income. But what exactly are they? Why do lenders ask for them? And how can you get hold of them? Let’s break it down.

What Are Tax Calculations (SA302s) and Tax Year Overviews?

A Tax Calculation (also called SA302) is a document issued by HM Revenue & Customs (HMRC) that summarises your income and the tax you’ve paid for a particular tax year. It’s essentially a snapshot of your tax return, showing your earnings and tax liability after all calculations have been made.
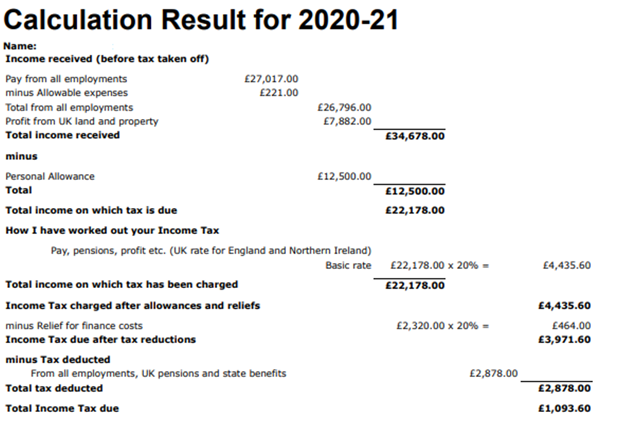
A Tax Year Overview is an official document provided by HMRC that summarises your tax position for a specific tax year. It shows the total amount of tax due, how much has already been paid, and whether there is any outstanding balance.
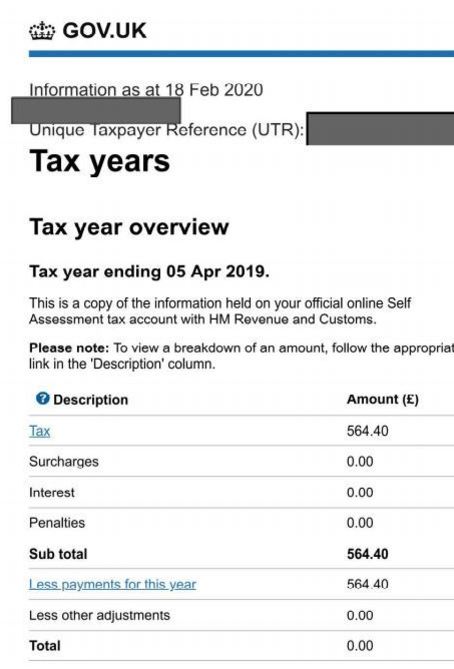
What is the difference between a tax return (SA100) and a tax overview?

A tax return shows all the client’s income details, including a return for any employed income submitted to the inland revenue. This will evidence the declared turnover, gross profit, expenditure, salary, etc. A tax overview, on the other hand, shows how much tax has been paid within the tax year.

Both documents serve as official proof of your income and tax history, which mortgage lenders rely on to assess your ability to repay the loan.

Do I need to declare rental income on my tax return?

Yes, you must declare any rental income on your tax return! The profit earned from this income source will be shown on the tax calculations under “income from land and property”.

Why Do Mortgage Lenders Need These Documents?

When you apply for a mortgage, lenders need to verify your income to decide how much they can safely lend you. For employed individuals, this usually involves payslips and P60s. However, if you’re self-employed or have irregular income, it can be more challenging to prove your earnings.

This is where SA302s and Tax Year Overviews come in. They provide lenders with a trusted, government-issued record of your income over the past few years, giving them confidence in your financial stability. Without these documents, your mortgage application could face delays or even rejection.

How Can You Obtain Your SA302 and Tax Year Overview?

There are several ways to get these documents from HMRC:

1. Online via your HMRC online account

  • Visit the HMRC website and log into your personal tax account.
  • Navigate to ‘Self Assessment’ and select ‘More Self Assessment Details’
  • You can view and download your SA302s and Tax Year Overviews for the relevant years.

You can get up to four years’ worth of information. Also – if you’re in a hurry – you’ll need to wait 72 hours after submitting your tax return before you can download your SA302.

2. Request by Phone

  • To request an SA302 or Tx year Overview by phone, you need to contact HMRC’s Self Assessment helpline on 0300 200 3310.
  • When calling HMRC, be prepared to provide some information to verify your identity and facilitate the request, such as your National Insurance number, your Unique Taxpayer Reference (UTR), details of the tax year(s) for which you need the SA302 and any other  information that may be required to confirm your identity.

Once your request is made, HMRC will process it and send the Tax Calculations and/ or Tax Year overviews to your registered address. The processing time can vary, so it is advisable to request the form well in advance.

3. Via Your Accountant

If you or your accountant submitted your Self-Assessment tax return by paper, you will be automatically sent your SA302 in the post.

if you or your accountant uses commercial software to perform your Self-Assessment tax return, you’ll need to use that software to access your proof of earnings or print your SA302s and Tax Year Overview from your HMRC online account. 

Final Tips:

  • Always ensure you have at least the last two to three years’ worth of SA302s or Tax Year Overviews, as most lenders typically require this period to fully assess your income.
  • Have these documents ready before you start the mortgage process to avoid delays.


Related

Flood Insurance is Changing

Flood Insurance is Changing

Flooding is something you should think about when taking out home insurance. And we are seeing major...

Read More >
Later-Life Mortgages Are Under the Microscope

Later-Life Mortgages Are Under the Microscope

Borrowing in later life is becoming increasingly relevant as people live and work for longer, retire...

Read More >
Over 55 and looking to move? You may have more options than you think

Over 55 and looking to move? You may have more options than you think

There’s a little-known option in the mortgage market that could help some people aged 55 and over b...

Read More >
Real Stories of Later Life Lending

Real Stories of Later Life Lending

There's a lot of noise around Later Life Lending, headlines about rates, regulation, and market ...

Read More >
AI Can Compare Mortgages. But Can It Replace Your Broker?

AI Can Compare Mortgages. But Can It Replace Your Broker?

For all the talk of AI tools and comparison sites reshaping financial services, the latest data on t...

Read More >
A New PM Is in No. 10 – Here’s What Actually Matters for Your Mortgage

A New PM Is in No. 10 – Here’s What Actually Matters for Your Mortgage

By now you'll have seen the news: Andy Burnham took office as Prime Minister on 20 July, becomin...

Read More >

What our clients say...

Stay Informed: Mortgage Tips & Trends

Flood Insurance is Changing

Flooding is something you should think about when taking out home insurance. And we are seeing major...
Read More

Statutory Sick Pay Has Changed – But Would It Cover Your Bills?

If you couldn't work because of illness or injury, how long could you keep paying your mortgage and ...
Read More

Later-Life Mortgages Are Under the Microscope

Borrowing in later life is becoming increasingly relevant as people live and work for longer, retire...
Read More

Rent Guarantee: Why Landlords May Want to Review Their Protection

Do you own a rental property? From 1 May, the new Renters’ Rights Act came into force, bringing maj...
Read More

Over 55 and looking to move? You may have more options than you think

There’s a little-known option in the mortgage market that could help some people aged 55 and over b...
Read More

Could your finances cope if your child became ill?

A recent report from MetLife UK highlights how quickly a child’s illness or injury can affect the w...
Read More

What Is a Health Cash Plan – and Could It Save You Money?

If dentist bills, new glasses, or physio have ever caught you off guard, there's a product that migh...
Read More

£7.84 Billion Reasons to Talk About Protection

Every day in 2025, protection insurers paid out £21.5 million to families across the UK. Money that ...
Read More

Real Stories of Later Life Lending

There's a lot of noise around Later Life Lending, headlines about rates, regulation, and market data...
Read More

AI Can Compare Mortgages. But Can It Replace Your Broker?

For all the talk of AI tools and comparison sites reshaping financial services, the latest data on t...
Read More


Fairview Financial Ltd is an appointed representative of The Right Mortgage Limited, which is authorised and regulated by the Financial Conduct Authority. Fairview Financial Ltd is registered in England and Wales no: 10912424. Registered office:  Calderwood House, 7 Montpellier Parade, Cheltenham, Gloucestershire, England, GL50 1UA

The guidance and/or advice contained within this website is subject to the UK regulatory regime and is therefore targeted at consumers based in the UK.

@ 2020 by Fairview Financial

Our Fees        

A fee may be charged for mortgage advice. The exact amount will depend on your circumstances.

Our standard fee for mortgages is £395 and this is paid when the mortgage is offered. We charge a fee of £295 for First-Time Buyers. Other fees may apply depending on the complexity of the work involved or loan amount. The maximum fee we can charge is £795.

Our standard fee for Equity Release is £895 and this is paid on completion.

We also receive a commission from the lender that will vary depending on the lender, product or other permissible factors. The nature of any commission model will be confirmed to you before you proceed. If we receive a commission, this will not affect the cost payable by you.

THINK CAREFULLY ABOUT SECURING OTHER DEBTS AGAINST YOUR HOME.

YOUR HOME OR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER DEBTS SECURED ON IT.

BUY TO LET MORTGAGES ARE NOT REGULATED BY THE FINANCIAL CONDUCT AUTHORITY.

EQUITY RELEASE: THIS IS A LIFETIME MORTGAGE. TO UNDERSTAND THE FEATURES AND RISKS, PLEASE ASK FOR A PERSONALISED ILLUSTRATION. CHECK THAT THIS MORTGAGE WILL MEET YOUR NEEDS IF YOU WANT TO MOVE OR SELL YOUR HOME OR YOU WANT YOUR FAMILY TO INHERIT IT. IF YOU ARE IN ANY DOUBT, SEEK INDEPENDENT ADVICE.


  • Back to top